South Carolina licensed attorneys must close real estate transactions because our Constitution gives our Supreme Court the power to define the practice of law, and that Court, beginning with the 1987 seminal case, State v. Buyers Service, has defined the practice of law to include closing real estate transactions.
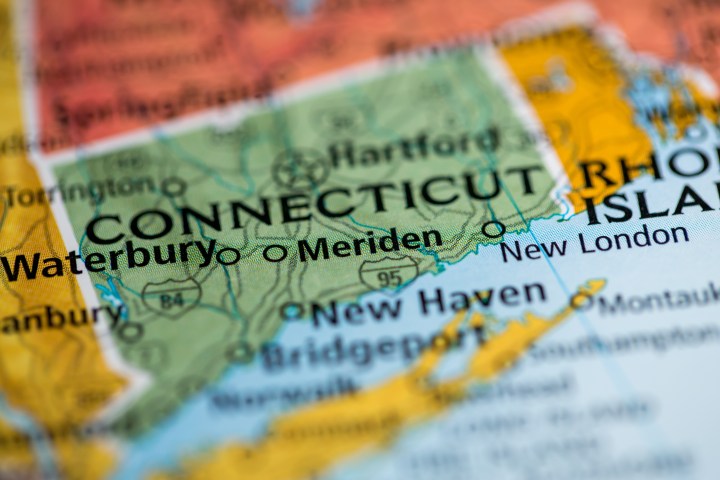
No explicit authority has required a similar result in Connecticut, but by custom, lawyers in Connecticut have routinely been involved in real estate closings. Beginning October 1, 2019, however, this long-standing practice will be required by statute as a result of the passage of Connecticut Senate Bill 320 (Public Act 99-88).
The new law defines “real estate closing” as follows:
- a mortgage loan transaction, other than a home equity line of credit transaction or any other loan transaction that does not involve the issuance of a lender’s or mortgagee’s policy of title insurance in connection with such transaction, to be secured by real property, or
- any transaction wherein consideration is paid by a party to such transaction to effectuate a change in the ownership of real property in Connecticut.
A violation of the new law will constitute a felony punishable by a $5,000 penalty or five years in jail.
It is interesting to me that a loan not involving title insurance does not require the involvement of an attorney. Why would a lender’s requirement of title insurance be determinative? I can envision the argument that foregoing title insurance and thereby foregoing the requirement of the involvement of a licensed attorney would greatly decrease closing costs. Both are protective of the interest of the lender. It seems to me that either title insurance OR a closing attorney would be more desirable than neither.
It is also interesting that there is no differentiation between residential and commercial transactions in the new Connecticut statute. All the South Carolina cases in this area have involved residential facts, and at least one well-respected commercial lawyer in Columbia believes the Court may not have intended to include commercial transactions, where sophisticated parties are almost always involved. Most commercial transactional lawyers believe commercial transactions must follow the residential line of cases. In Connecticut, it seems clear by the statutory definitions that lawyers are required for commercial closings.
Equity lines not being included under the purview of the new law seems counterintuitive. A consumer can get into as much or more trouble with an equity line as with any first or second mortgage.
And my final thought is that the statute doesn’t seem to define who the attorney must represent in the closing. The law states “no person shall conduct a real estate closing unless such person has been admitted as an attorney in this state.” South Carolina cases are clear that the protections are established for the consumer borrower.
In any event, I believe most South Carolina dirt lawyers would agree with me that we like the fact that Connecticut agrees with South Carolina and wish other states would follow suit!




 The South Carolina Department of Revenue issued Revenue Ruling #17-5 concerning Deed Recording Fees on August 28, 2017. This advisory ruling supersedes Revenue Ruling #15-3.
 The Revenue Ruling addressed whether a vacation home is a “business” by stating that it is not a business if IRC §280A limits the deduction of vacation home rental expenses. That’s a little deep for dirt lawyers, so the safe approach is to always obtain a certificate of compliance or Transferor Affidavit when you close on that rental home in Pawleys Island.
 We’re learning for the first time what the CFPB considers the top mistakes being made by lenders in mortgage originations under TRID. CFPB’s September 2017 Supervisory Highlights reports on the Bureau’s first round of mortgage origination compliance examinations. Prior to these examinations, the Bureau refused to provide a grace period for lender compliance but stated publicly that it would be sensitive to the progress made by lenders who focused on making good faith efforts to comply with the rule.

