Something Spooky Is Lurking in Your Survey: The Rise of Survey Fraud

Standard

October is the season for ghosts, goblins, haunted houses, and things that go bump in the night. But for real estate lawyers and title professionals, there may be something even scarier hiding in a closing file: a fraudulent survey.  And unfortunately, this one is not wearing a costume.

An emerging form of real estate fraud involves property surveys that have been fraudulently altered or, in some instances, completely fabricated. With today’s sophisticated graphic-editing software and artificial intelligence tools, changing a document has become frighteningly easy. Even worse, the finished product can look remarkably authentic. That means the survey sitting in your closing file may not always be what it appears to be.

A Survey With a Few Tricks

Fraud-prevention reports have described schemes in which existing surveys were allegedly manipulated to conceal or misrepresent conditions affecting property. Examples have included an existing survey allegedly altered to remove an improvement, as well as a fabricated survey allegedly omitting structures encroaching into an easement.

Now you see it. Now you don’t.  These are not harmless edits. A survey can play an important role in identifying or evaluating boundaries, improvements, easements, encroachments, and other physical matters that may affect the title to or use of the property.

But remember that the survey and title examination serve different functions. A clean-looking survey does not eliminate matters disclosed by the public record, and a survey should not be treated as a substitute for a proper title examination. When the survey, legal description, recorded documents, and conditions on the ground do not seem to tell the same story, that discrepancy deserves further investigation.

Look for the Survey’s Skeletons

Unfortunately, there may not be one obvious clue that a survey has been manipulated. Still, a few red flags should cause you to take a closer look:

  • Inconsistent fonts, text sizes, spacing, or formatting.
  • Letters or numbers that appear to float, lean, or otherwise differ from surrounding text.
  • Smudges, unusually faint lines, white areas, or other indications that information may have been removed or replaced.
  • A surveyor’s signature or seal that appears misaligned, copied and pasted, or visually disconnected from the document.
  • Differences between the property’s legal description and what is depicted on the survey.
  • A recorded easement or other matter revealed by the title examination that an apparent current survey unexpectedly fails to depict or reference.
  • Electronic file creation or modification dates that do not reasonably correspond with the purported date of the survey or revision.

None of these things, standing alone, necessarily proves fraud. Documents are frequently scanned, copied, downloaded, combined, and converted into different electronic formats. Unusual metadata or formatting should therefore be treated as a reason to ask questions, not proof that a survey has been fraudulently altered.

Don’t Be Haunted by a Fake Survey

Fortunately, one of the best defenses against survey fraud is surprisingly low-tech: independent verification.  Whenever practicable, obtain the survey directly from the licensed surveyor or independently confirm with the surveyor that the version provided for the transaction is authentic.  If a survey comes from the seller, buyer, real estate agent, or another third party, consider independently identifying and contacting the surveyor to verify the document.

And here is an important point: do not rely exclusively on the phone number or email address printed on a questionable survey.  If someone has gone to the trouble of fabricating a survey, creating fraudulent contact information is not much of a leap. Independently locating the surveyor’s legitimate contact information provides an additional safeguard.

The Same Old Fraud Lesson, Wearing a New Costume

Title professionals have already learned an important lesson from years of combating wire fraud and other real estate scams: trust but verify. The same principle applies here.

Technology continues to make document manipulation easier and more convincing. That does not mean every imperfect-looking survey should send the closing attorney running from the building like the last scene of a horror movie. It does mean we should resist accepting a document at face value when something does not look right. Fraudsters may have some new tricks.

Our best treat remains the same: slow down, ask questions, compare the survey with the title evidence, and independently verify before relying on the document. Because when it comes to property surveys, the scariest problems may be the ones somebody has carefully erased.


Cybersecurity Threats and Their Impact on Real Estate Transactions

Standard

Imagine arriving at your real estate closing only to learn that the county’s property records are unavailable. If the documents can’t be recorded, then the transaction may be left hanging in the air. Depending on lender funding requirements, the closing attorney may not be able to disburse the funds, and the buyer may not be able to receive their keys until recording is available. It sounds far-fetched, but it’s exactly the type of disruption that recent cyber-attacks on county governments have made possible.

Most people never think about their county recording office until they’re buying or selling real estate. Deeds, mortgages, easements, plats, liens, and other documents are quietly recorded every day, creating the public record that establishes who owns property and what interests affect it. It’s a system that has worked for generations because it relies on one simple principle: the public records must be accurate, complete, and accessible.

Recent events in South Carolina serve as a reminder that this system is more fragile than many people realize.

A recent cyber attack disrupted access to property records and other county services, temporarily preventing normal operations. While the details of the investigation continue to emerge, the incident highlights just how dependent modern real estate transactions have become on digital access to public records. Unfortunately, this is not an isolated event. Several South Carolina counties have experienced technology failures, ransomware attacks, or other disruptions in recent years.

Cyber security, however, is only one challenge facing county recording offices.

Many counties across the state operate with limited budgets and skeleton crews. Employees often process hundreds of documents each day while balancing increasing demands and aging technology. Even the most dedicated public servants can struggle when resources are stretched thin. Under staffing and insufficient training increase the likelihood of recording errors, indexing mistakes, or delays in processing documents – all of which can create headaches for property owners years later.

The integrity of the public record is essential because virtually every real estate transaction depends on it.

Before issuing title insurance, conducting a closing, or approving a mortgage loan, attorneys and title professionals examine the public records to confirm ownership and identify any issues affecting the property. They are looking for deeds that properly transferred title, unreleased mortgages, judgments, tax liens, easements, restrictive covenants, and countless other matters that could affect ownership rights.

If those records are unavailable because of a cyber attack, the transaction may be delayed. Buyers may not be able to close on schedule. Sellers may miss contractual deadlines. Lenders may refuse to fund loans until title can be verified. Even a short interruption can create significant inconvenience for everyone involved.

More concerning are situations where records have been altered, corrupted, or improperly indexed. The public recording system functions because people can trust that what they find is complete and accurate. Preserving that trust requires not only secure computer systems but also adequate staffing, proper training, and ongoing investment in the offices that maintain these records.

Although county governments bear much of the responsibility for protecting these systems, cybercriminals often gain access through surprisingly simple methods.

Many cybersecurity incidents begin not with sophisticated hacking tools but with social engineering. Rather than attacking computers directly, criminals manipulate people into providing passwords, opening malicious attachments, or clicking fraudulent links. These phishing emails are designed to look legitimate and frequently impersonate trusted organizations, coworkers, financial institutions, or government agencies.

While this blog focuses on real estate law, cyber attacks and scams aren’t limited to real estate transactions. Anyone, not just government employees, can become a target. A few simple precautions can dramatically reduce the risk of becoming a victim. Be cautious of unexpected emails requesting urgent action. Verify unusual requests through a separate phone call or trusted contact information rather than responding directly to the email. Avoid opening attachments or clicking links unless you are confident they are legitimate. Enable multi-factor authentication (“MFA”) whenever possible, and keep software updated to address known security vulnerabilities.

These habits protect more than your personal information. They help protect the institutions that communities depend upon every day.

County recording offices rarely make headlines when everything is working properly. Yet they perform one of the most important functions in our legal system by preserving the history of property ownership and ensuring that buyers, sellers, lenders, and attorneys can rely on the public record.

As counties continue modernizing their technology, cybersecurity must remain a priority. At the same time, we should not overlook the importance of investing in the people responsible for maintaining these records. Secure systems, well-trained staff, and accurate public records are not simply administrative conveniences: they are essential to protecting property rights and keeping South Carolina’s real estate market functioning smoothly.

Surfside Beach and the Continuing Threat of Business Email Compromise

Standard

According to news reports, the town of Surfside Beach may be one of the latest victims of a business email compromise-type fraud attack. Unfortunately, early reports suggest that the town may have lost over half a million dollars to scammers. South Carolina’s State Law Enforcement Division is actively investigating this incident, so the information we have is limited and unproven, but if true this amount would represent a loss of funds equal to approximately 2.6% of the town’s 2025-2026 budget.

Wildcat Construction was engaged by the town to do some work on its public utilities, and one of its bills, in the amount of $545,598.30, was due for payment. On March 13, 2026, the town indicates it initiated an ACH payment to what they thought was an account belonging to Wildcat, but Wildcat says that it has no such account and that it had requested payment by check. The town released a public statement in which it acknowledged it had “identified a potential cybersecurity incident involving its email environment,” and reported the incident to law enforcement. Details about what exactly may have happened internally at the town level are pretty scant. While SLED is investigating, Wildcat maintains that it has not received the funds, and that it is still entitled to be paid. It is easy to imagine how a scammer might have sent a “spoofed” email to a Town employee, pretending to be an accounts receivable clerk for Wildcat, with a fake set of payment instructions for the Wildcat invoice. The same type of “spoof” attack happens all too often in real estate deals where the closing attorney is gathering invoices and payment instructions. If the Town employee failed to properly verify those payment instructions, then just like the danger of wire fraud in a real estate transaction, the funds could have been sent to a fraudster instead of the correct party.

Data published by the FBI’s Internet Crime Complaint Center, which tracks and reports cyber-crime involving US interests, indicates that both the number of cyber-crimes against, and the amount of property lost by, Americans continues to skyrocket. The IC3 reports that in 2025, it received a total 1,008,597 of cyber-crime complaints for all types of cyber-crime, and it tracked over $20.8 Billion in total losses related to cyber-crimes. The clear indication here is that cyber-criminals are increasing their attacks on our businesses, and are succeeding in stealing more of our money.  

This incident is yet another example highlighting the importance of verifying payment instructions with a known, trusted contact. That includes not only the routing/account numbers, but also the form of payment. In this example, Wildcat says it told Surfside they wanted a check, but the payment was made via ACH to an account that Wildcat says it did not provide to the Town.

While the “worst case scenario” impact on Surfside Beach, even if these funds are permanently lost, looks like it would be below 3% of the town’s overall annual budget, the risk to South Carolina lawyers of wire fraud and business email compromise is potentially much more dire. For a small or solo real estate-focused law firm whose annual fee revenues might be closer to the $1,000,000.00-mark, loss of funds for a mortgage payoff could be much higher as a percentage of the firm’s budget. If we assume that a typical mortgage payoff for a SC home might be around $250,000.00, then it’s easy to see how that amount, when targeted by fraudsters, could be a devastating loss for a small firm. And, while this particular example was not a real estate law firm, it demonstrates that the fraudsters are out there actively targeting anyone they think they can, and that no one is immune to their attacks.

Stay vigilant out there, folks!

Graceland Fraudster Does the Jailhouse Rock

Standard
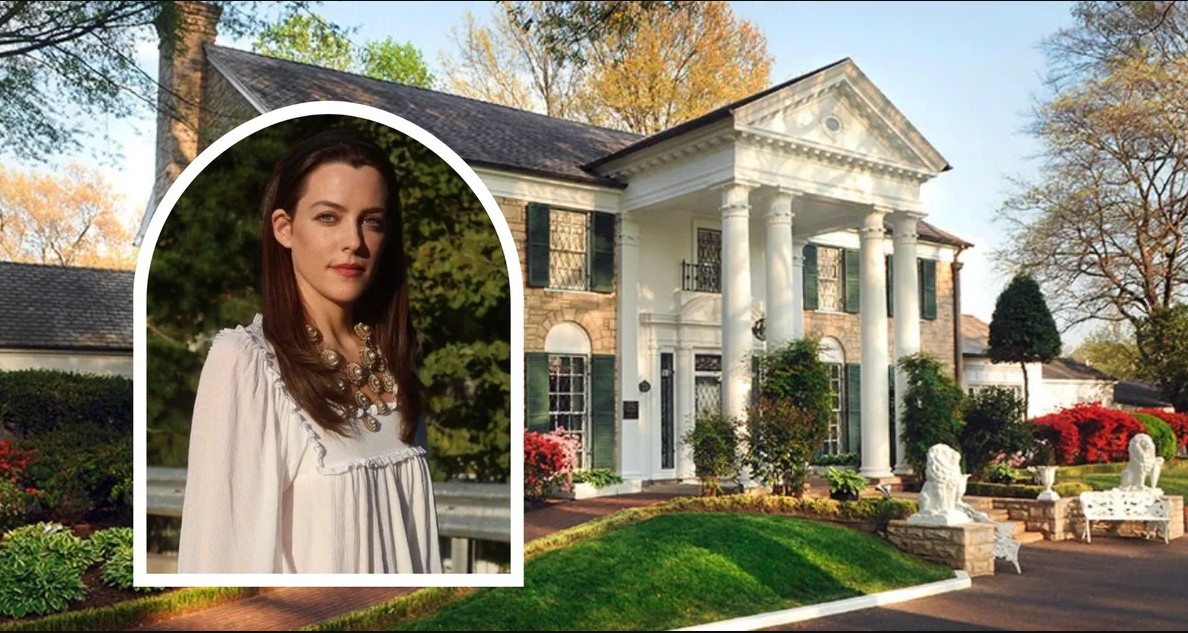
Riley Keough, inset, with Graceland

Lisa Findley, a woman from the Ozarks with a known history of petty crime, was sentenced to 57 months in federal prison last month after pleading guilty to mail fraud. The charge stemmed from a bizarre scheme in which she attempted to secure a $3 million payoff using a fake loan backed by a fraudulent mortgage on Graceland, the former home of Elvis Presley.

Using at least four different alter egos, Findley attempted to convince lawyers for the estate of the late Lisa Marie Pressley1 and of her daughter, actress Riley Keough2, that a non-existent company called Naussany Investments & Private Lending, LLC, had loaned Lisa Marie $3,800,000 secured by the iconic home.

Findley supported the scheme by forging the signatures of Lisa Marie and a real Florida notary on fake loan documents. She even went so far as to threaten foreclosure. While attorneys for the Presley estate grew suspicious minds, Findley escalated her efforts by filing a creditor’s claim against the estate in California and separately recording a fraudulent Note and Deed of Trust in Tennessee land records. Despite making little progress, she pressed the matter by publishing a Notice of Foreclosure Sale in the Memphis Commercial Appeal.

While the Pressley attorneys rushed to obtain an injunction to keep the Jungle Room in the family’s domain, reporters and law enforcement began to close in on what proved to be an easy web to unweave. Perhaps feeling caught in a trap, Findlay’s alter egos abruptly disclaimed any connection to the loan and directed attention to a third alter ego.  After some token resistance, this alter ego confessed in an email written in Spanish – don’t ask me why – to that he was really a Nigerian scam artist and that the authorities should seek him in that fine African nation. 

This final effort to by Findlay was … not successful. Despite asking the judge to don’t be cruel, she will now spend a blue Christmas in a federal penitentiary for the next several winters.

In all seriousness, this scheme highlights both the growing prevalence of “imposter” frauds and the lengths and doggedness which fraudsters will pursue them. While this imposter chose very poorly in her attempted fraud target, the methods used should be a warning to all real estate professionals of what kind of methods they might run across in a scam. You could see how a less ambitious scheme could have been a little more credible and come closer to success.  


[1] Daughter of the King of Rock and Roll, and wife to the King of Pop, Michael Jackson! Plus, her mom was on Dallas! Pure royalty. 

[2] Keough was great in the Amazon mini-series ‘Daisy Jones and the Six.’  Definitely worth the watch if you have not seen it.

[3] Foreclosures can proceed non-judicially in Tennessee, which means creditors may in many circumstances sell property without court oversight.  

Pay attention to ALTA’s new seller impersonation memo

Standard

American Land Title Association recently published a memorandum concerning seller impersonation fraud in real estate. You can read the memo in its entirety here.

We have always had to be on the lookout for fraudsters in real estate in South Carolina. Do you remember the infamous Matthew Cox who came to South Carolina after a fraud binge in Florida and Atlanta?

I’ll never forget the name, Matthew Cox, or the telephone call that tipped us off that we had a serious mortgage fraud situation here in Columbia. Long before the housing bubble popped, an attorney called to let us know what was going on that day in the Richland County ROD office. Representatives of several closing offices were recording mortgages describing the same two residential properties in Blythewood, as if the properties had been refinanced multiple times in the same day by different closing offices.

At first, we thought our company and our attorney agent were in the clear because our mortgage got to record first. South Carolina is a race notice state and getting to record first matters. Later, we learned that deeds to the so-called borrower were forged, so there was no safety for anyone involved in this seedy scenario. Thousands of dollars were lost.

Next, we learned about the two fraudsters who had moved to Columbia from Florida through Atlanta to work their mischief here. The two names were Matthew Cox and Rebecca Hauck. We heard that Cox had been in the mortgage lending business in Florida, where he got into trouble for faking loan documents. He had the guts to write a novel about his antics when he lost his brokerage license and needed funds, but the novel was never published. With funds running low, Cox and his girlfriend, Hauck, moved to Atlanta and then Columbia to continue their mortgage fraud efforts.

We didn’t hear more from the pair until several years later, when we heard they had thankfully been arrested and sent to federal prison.

The crimes perpetuated by Cox and Hauck were made easier by the housing bubble itself. Everything was inflated and values were hard to nail down. And closings were occurring at a lightening pace.

The new memo from ALTA says fraudsters are using owner’s Social Security and driver’s license numbers as well as notary credentials in these transactions. They, of course, use emails and text messages to mask their identity and commit fraud from any location.

The red flags remain the same:

  • Vacant real estate;
  • No outstanding mortgages;
  • For sale below market value;
  • Seller wants a quick sale;
  • Seller wants a cash buyer;
  • Seller refuses to attend the closing and claims to be out of the country;
  • Seller is difficult to reach by telephone;
  • Seller demands the proceeds be wired;
  • Seller refuses to complete multifactor authentication or identity verification;
  • Seller wants to use their own notary;

Be careful out there, dirt lawyers! Use your common sense and insist on verifications of identity.  ALTA’s memo has several useful tips.

Beware of recent seller imposter fraud

Standard

Fraudsters are creative, changing their schemes to meet the current market at every turn! Seller imposter fraud has been an issue for several years, but we’re hearing new reports in South Carolina. My favorite title insurance company and former employer, Chicago Title, sent out its third memorandum about seller imposter fraud on December 8. I wanted to make sure all readers of this blog are aware of the new efforts by fraudsters.

Several dirt lawyers in Charleston have reported variations in the seller imposter fraud arena in the last month.

Here are warning signs Chicago Title’s memo highlights:

  • The property involved is often unimproved.
  • The property is often advertised for sale through internet-based listing services.
  • The property is often listed at a price less than fair market value.
  • Contact with the imposter seller is often only by email.
  • The purported seller declines any requested in-person contact.
  • The purported seller supplies identification only by photocopy or teleconference.
  • The purported seller suggests executing documents outside of closing.
  • The purported seller suggests acting via power of attorney.

If you see any of these factors in your closings, pay particular attention to the identity of the seller. Advise your staff of these matters and advise them to allow a second set of eyes to review any questionable practices suggested by sellers.

As the excellent underwriting staff of Chicago Title reports, most of these attempts to steal are entirely preventable by paying attention to documents and taking extra steps to verify the identities of the parties involved in your closings.

South Carolina lawyers have prevented these fraud attempts by using the following tactics:

  • They carefully review documents for irregularities and inconsistencies.
  • They verify seller identity through contact information available in the public records or through other trusted sources.
  • They verify foreign identities and notarizations by contact with appropriate embassies.
  • They confirm witnesses and notorizations with the notary whose signature appears on the documents.
  • They compare package tracking information and wiring instructions to the purported location of the seller.

Please be careful out there and advise your staff members of these issues.

Some (relatively) new scam tips

Standard

If I told you how many articles I’ve written about fraud and scams, you’d think I’m much older than I am, so we won’t go there. But I am old enough to be retired. My husband and I both worked for large corporations who kept us current on scams of all kinds. In retirement, we must read numerous sources to make sure we keep ourselves safe online and otherwise.

The Washington Post, one of my favorite newspapers, published an article on September 6 entitled “Yes, it’s a scam; Simple tips to help you spot online fraud.” You can read it here.  

The first tip makes so much sense: “Have “the talk” with family members.” This is so important! Tell your aging parents, your teenagers who spend a considerable portion of their lives online, and everyone in between the tricks you learn from your practice and your title insurance company about safety online. As painful as it may be to assist your elderly family members with their computer issues, keeping them safe from scams will save you from having to unwind the problems. Tell your family members to come to you to “gut-check”, as the article advises, suspicious messages and phone calls.

The second tip involves social media. The article advises that privacy settings can make it significantly harder for cybercriminals to successfully target you and your family members. Read the article for the details.

The third tip is my mantra: stay current! Using current events for unjust enrichment is a prime strategy of scammers. The article reports that within 24 hours of President Biden’s announcement of the student loan forgiveness program, The Federal Trade Commission released a warning about student loan scams. Updates for all of us are available at Fraud.org, a project of the National Consumers League. Make one of your employees responsible for reviewing and reporting on the great information from that site. And make sure your family members know about it.

I love this one: “Assume that people or companies aren’t who they say they are.” As lawyers, we’re naturally and by education skeptical. Make sure those around you approach the internet and telephone as skeptically as you do.

This one is great: “Verify everything using a different channel.” Title insurance companies have been telling their agents for years (decades!) to verify wiring instructions by making a telephone call using a known and trusted telephone number. This advice can be used in other areas of online life. Use official customer service numbers and websites. Call your bank! Call or text a friend who asks for money via social media. The article advises the use of AARP’s free telephone service to ask about possible scams: 877-908-3360.

The article advises all of us to memorize the signs that something is a scam:

  • You didn’t initiate the conversation.
  • You won something.
  • You are panicked:  scammers want to create a sense of urgency.
  • It involves fast payment methods: peer to peer payment apps, for example.
  • There are payment complications. For example, the scammer will offer to pay over an app like Zelle, say there’s a problem, then ask for your email address so they can send a fake email to get your information.
  • They want information.
  • Something doesn’t feel right.

Stay current, keep your office current, and keep your family members current!

Myrtle Beach article points to current fraud cases

Standard

The Myrtle Beach Sun News published an article on September 5 entitled, “They were conned out of their dream beach home, lawsuit says. These are common SC scams.”  You can read the article here.

Those of us who have worked in the real estate industry for years have heard of (or been bitten by) various iterations of real estate fraud schemes. These schemes change routinely as the fraudsters become more sophisticated. Thankfully, we are becoming more informed and therefore more sophisticated ourselves. But this article is an excellent reminder.

The article recounts the tale of a North Carolina couple, Jeremy and Candice Pedley, who spent years saving before finally acting on their dream of owning a family vacation home in North Myrtle Beach. The Pedleys entered into a contract last November to purchase a condo in in a gated community for $380,000. Unfortunately, a third party hacked into the real estate agent’s emails, impersonated their closing attorney, and convinced he Pedleys so wire their funds to a bank account in Rock Hill.

The hacking effort requested the exact number the Pedleys were expecting to wire, $86,183.81. This fact convinced the Pedleys that the fraudulent instructions were legitimate. According to the article, they have been able to recover about $36,000 of the lost funds. They were unable to complete the purchase of their dream condominium.

Columbia attorney Dave Maxfield is representing the Pedleys in a lawsuit attempting to recover their funds. According to the article, Maxfield told the Sun News that banks should do a better job stopping fraudulent accounts from being used, and real estate agents and attorneys need to warn clients about the pitfalls of wiring funds.

The article then details a few other common scams outlined by The S.C. Department of Consumer Affairs.

One such scheme creates fake rental listings promising low rent, immediate availability, and great amenities. The goal is to trick renters into transferring funds before they are tipped off that the listings don’t exist.

Another scheme notifies consumers that they have won the lottery, requesting, of course, some sort of fee or tax to receive the alleged winnings. Pressure is applied to “act now”.

Finally, the article discussed fake debt collectors. Fraudsters impersonate government authorities and attempt to convince consumers to pay off debt. These schemes typically request the target to pay a fraction of the amount they owe in return for full debt forgiveness. Threats of arrest are often used to apply pressure.

Please keep yourself and your staff members educated about all the current schemes. Your title insurance company should be a great source of current information. And please give your staff members permission to slow down and use the time they need to think through the facts of your transactions. I believe time is the key. The very smart individuals you employ, if properly armed with the necessary information and education, should be able to thwart most of these schemes, if they are given sufficient time to analyze the communications that hit their inboxes daily.

New fraud warning from Chicago Title

Standard

It goes without saying that one of the most important partnerships for a real estate lawyer is a great title insurance company. I am biased, but in my opinion, there is no better title insurance company doing business in South Carolina than Chicago Title.

This week, a warning was issued from Chicago Title about a new and very specific fraud scheme that I want to share with all South Carolina practitioners.

Chicago Title received two reports last week of fraudsters apparently operating out of Houston. The fraudsters posed as owners of South Carolina properties and listed the properties for sale on Zillow. Mail away cash closings were scheduled with local real estate lawyers. In both cases, the fraudsters provided presumably fake identification and deeds to closing attorneys.

In the first case, the closing attorney very astutely foiled the scheme when he determined the signatures on the deed appeared suspicious. He contacted the New York notary who purportedly notarized the deed. She reported her seal had been stolen and used in at least one successful fraudulent scheme. The lawyer also learned from Federal Express that the deed had been sent from Houston rather than New York, where the seller was purportedly located. The transaction was stopped.

Unfortunately, the second transaction was not stopped.  This seller package also originated in Houston. The fraudster’s telephone number appears on Zillow listing for properties in multiple states. Houston law enforcement has been notified and is opening an investigation.

Any mail away closings should be particularly scrutinized. If you conduct a closing with an unfamiliar seller, you should be especially vigilant in confirming the identities of the parties. Use more than one set of eyes in your office! Anything that appears unusual should be examined carefully. Give your staff the flexibility to slow down and carefully examine each document. Tell them to bring any unusual document to you. Check behind your staff! A great real estate paralegal is invaluable, but we spent three years in law school learning to spot issues. Use those issue-spotting skills to foil these fraudsters!

Be careful and good luck out there!