One of President Trump’s first official actions affects housing

Standard

presidential-seal

The Federal Housing Administration (FHA) announced on January 9 that it planned to reduce mortgage insurance premiums effective January 27. Mortgage insurance protects lenders from borrower defaults and is common where the down payment is less than 20%.

The Democratic view of this issue is that sufficient reserves and four years of economic growth allowed the FHA to pass along some modest savings to consumers. Additionally, the move was viewed as an attempt to help first-time and lower income home buyers to access the market at a time when mortgage rates were rising.

The Republican view is that such reductions put taxpayers at risk by decreasing the funds the FHA has to deal with mortgage defaults. In other words, taxpayers might be at a greater risk for footing the bill for another bailout if FHA’s reserves were reduced.

President Trump’s advisors criticized the Obama administration for adopting new policies as it prepared to leave office. During Dr. Ben Carson’s confirmation hearing for Secretary of the Department of Housing and Urban Development (HUD), FHA’s parent agency, he expressed disappointment that the cut was announced so late in President Obama’s term.

On January 20, shortly after he was sworn in, as one of his first substantive actions, President Trump undid this new policy before it took effect by signing an executive order.

HUD then issued a letter stating that more analysis is needed before changes are made, and the rates will remain the same for the time being.

It appears industry groups may have differing opinions on whether President Trump’s executive order will affect home buying. Will this action reduce opportunities for first-time buyers? Or will it eventually allow FHA’s reserves to be increased to a point where it can offer more services to borrowers? Industry groups will continue to weigh in, and this blog will continue to keep South Carolina dirt lawyers posted on developments.

A little mundane, but useful, information for your New Year

Standard

paperwork-stacks

York County’s Register of Deeds office recently informed local dirt lawyers that it will begin using a new system on January 23. The new system will require labels containing recording information to be attached to recorded documents.

This County will require a three-inch margin at the top or bottom of the front page of each recorded document. Documents that do not meet the margin requirement may be rejected because the label may conceal a portion of the document.

I am confident York County lawyers are informed of this development but wanted to get the word out to the remainder of the state to benefit lawyers who may handle a transaction in that County from time to time.

Goodbye old friend

Standard

And hello 2017!

I bought a car on the first business day of 2017.

For most folks, buying a car is not a big deal, but I am definitely not a car person!  I drove my mother’s last car for almost eleven years after her death in 2006 and was embarrassed to shed a few tears at the dealership when I sentimentally traded it in on January 2. That car has 200,000 miles on its odometer! It’s still in great running condition, and I hope it finds a good home with someone, maybe a teenager, who needs safe and inexpensive transportation. Before my mother’s car, I drove a car I bought from a deceased friend’s estate. Are you detecting a pattern in my vehicular history?  Until this week, no car dealership had made a dime on me in the past 15 years!

My colleague and friend, Tom Dunlop, on the other hand, is definitely a car person. He currently drives a bright red late model Mercedes which he will upgrade this spring for the mere reason that two years have passed. His dealership loves him! In addition to trading every two years, Tom takes donuts to the staff when his car is serviced. What a nice guy! We’ve enjoyed that shiny red Mercedes as our lunch vehicle and can’t wait to see what Tom decides will be our new fancy ride in the spring.

new-year-new-startWhy is this car talk relevant to dirt law in 2017? It’s relevant because our success in the housing industry this year may depend on whether Americans and specifically South Carolinians are really home ownership people.

There are some reasons for concern. Interest rates are climbing. The mortgage interest rate deduction is under attack in Congress. The future of the CFPB may be precarious under the new administration and because of pending litigation challenging its constitutionality.  Some financial advisers are recommending renting as a better economic alternative for many Americans. Some retirees are being advised to sell the large homes where they raised their families in exchange for nifty, low-maintenance town homes, condominiums and even rental apartments.

But unlike my personal lack of thirst for new cars, I believe many Americans and many South Carolinians have an enduring thirst for new and upgraded residences. And I believe their thirst is most often quenched only by purchasing those residences. We have been taught that home ownership is an excellent investment vehicle coupled with a tax advantage. This advice goes back several generations. This wisdom is so ingrained that the counsel to retirees to rent shocked me! I had to read it from several sources to believe it was serious and sound advice for some folks.

And, thankfully, the economy is continuing to improve. Zillow is reporting that the U.S. housing market has regained all the value it lost during the housing crisis. South Carolina is particularly poised for success. Charleston is one of the fastest growing markets in the country. Hilton Head is digging out and rebuilding from Hurricane Matthew. The Rock Hill/Fort Mill area is growing toward Charlotte rapidly. It is impossible to ride around Myrtle Beach, Greenville and even Columbia without dodging construction activity. My own office’s numbers have improved during 2016, and I budgeted up for 2017. I suspect most South Carolina dirt lawyers are looking for a better year in 2017 than in 2016 assuming they can maintain their momentum and sustain the excellent staffing that momentum requires.

I am optimistic!  Here’s hoping Americans and South Carolinians continue to be home ownership people. And here’s hoping 2017 is a healthy, happy and prosperous year for you!

The housing industry is crying Bah! Humbug!

Standard

Congress may eliminate mortgage interest deduction

Mike Goodwin, the “Bow Tie Comedian” based here in Columbia, mike-goodwin-bowtie-comedianentertained us during lunch at our recent Chicago Title seminar. A joke that bubbled up through his very funny presentation was a line his mother used to keep him on the straight and narrow during his childhood, “what you NOT gonna do is…..”

For example, she would say, what you NOT gonna do is to stand there and hold that refrigerator door open while you try to decide what you want to eat. During one lull in the laughter, Mike said to us, “what you NOT gonna do is sit there and not laugh at my jokes.” (So we laughed.)

While some of us believe America is about to be made great again, some of us might like to borrow Mike’s line to deliver a Bah! Humbug! message to Congress:  What you NOT gonna do is to eliminate, or effectively reduce the effectiveness of, the mortgage interest deduction. Many homebuilders, lenders and real estate agents (and South Carolina dirt lawyers) believe that’s one thing we don’t need 2017.

The mortgage interest deduction is a major driver of the housing market. One reason American dreamers strive for home ownership is to take advantage of this tax break. That, along with the property tax deduction, the points deduction, the PMI deduction and the home office deduction, make owning a home a wise move from a tax standpoint. Eliminating or reducing the effectiveness of the home interest deduction, which many consider as American as apple pie, might put a damper on the improved economy we have been experiencing in 2016.

But that approach is definitely going to be under consideration by Congress, and players in the housing industry are preparing to defend the deduction. The plan under consideration involves not a direct elimination of the deduction, but an indirect attack via an increase of the standardized deductions, now at $6,300 for a single taxpayer and $12,600 for married taxpayers filing jointly. By doubling these standard deductions, many taxpayers would have no need to take the mortgage interest deduction.

The mortgage interest deduction is the largest deduction currently available to homeowners, allowing a write-off of interest from up to a $500,000 loan for a single taxpayer and up to a $1 million loan for joint filers. The deduction is especially important during the early years of a mortgage when the majority of payments are applied to interest rather than principal.

megaphone-businessman-2

“Congress … what you NOT gonna do is … “

If a single taxpayer pays mortgage interest of $8,000 in the first of home ownership, for example, that amount exceeds the current standard deduction of $6,300, and that taxpayer would itemize to claim a better tax break. If the standardized deduction is doubled, itemization is much less likely.

President-Elect Trump’s nominee for Secretary of the Treasury, Steven Mnuchin, has stated that the administration is planning to create the largest tax change since Reagan. Simplifying the tax code is one of the stated objectives, and a larger standard deduction is one method of simplification. In addition to the mortgage interest deduction, the charitable deduction would be affected in a similar manner.  Some say that as the standard deduction goes up, the incentive to give is reduced.

Any step that would reduce incentives for homeownership would likely encourage renting rather than buying. Home values might suffer, and the housing industry might suffer as well.

All Americans are interested in the changes that are about to happen, and those of us in the housing industry may be more interested than most! I have already seen prognosticators reducing their optimism about 2017, but I just got off the phone with a local wise man. He said that I should relax. 2017 is going to be a banner year, he said, because America is going to be great again. I hope he’s right!

What’s Happening with Our Nation’s Malls?

Standard

Three recent Realtor® Magazine articles explore the rise and fall of our nation’s malls. I highly recommend that you read the interesting articles entitled “Dying Suburbia Malls Become Housing Mecca” (October 7); “Will the Death of Malls Save the Suburbs?” (October 6); and “The Nation’s Malls are Getting Major Redo” (July 19) for the full story. The October 6 article, the most comprehensive, was written by Clare Trapasso.

empty-mall

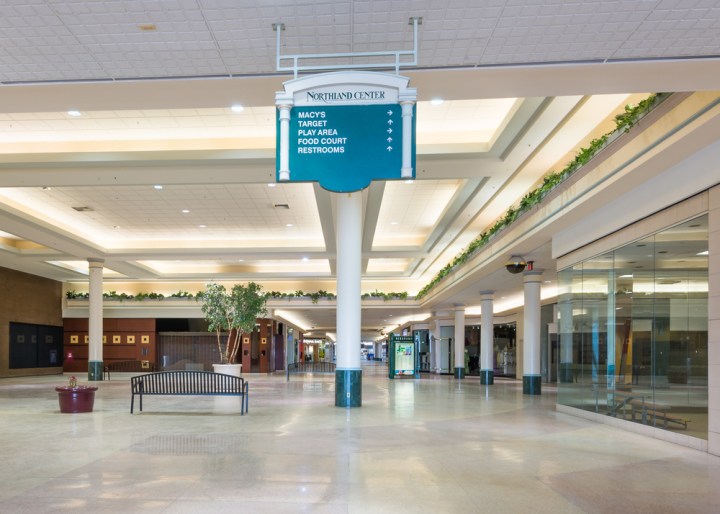
Northland Center, largest mall in the world when it opened in 1954, is now closed.

Summarizing, enclosed malls are basically a post-World War II American phenomenon. These hulking projects vary in size but may be as large as 1.2 million square feet of shopping, dining, movie and other recreation space. In 1970, there were around 300 enclosed malls across the country. By 1996, this number had increased to around 1,040.  Now major stores are closing, and many malls are going dark.

The October 7 article quotes Ellen Dunham-Jones, an urban design professor at Georgia Tech, with the statistic that around 200 malls have closed down in the past two years.

What happened to our malls? It’s a simple answer: the internet.

More and more shoppers are skipping brick-and-mortar retailers to shop online. The malls that are surviving appear to be those with high-end shops that provide luxury experiences shoppers can’t get online. Dunham-Jones pointed to valet parking and chic boutiques with fitting rooms that can take pictures from different angles.

Landlords who once courted department store anchors are now looking for funky boutiques and innovative restaurants. The prediction is that more and more enclosed malls will close, and the question becomes, what will happen to the underlying real estate?

These articles, targeting Realtors®, indicate readers may be renting and selling these properties for mixed-use purposes, including housing! Some malls are being converted into public parks, office space, medical complexes, sports facilities, micro-apartments and condominiums. The theory is that a person can live in an apartment or condo in one of these retrofitted malls and walk to shopping, movie theaters and doctors’ offices.

Some developers like the idea of transforming these acres of flat real estate with existing infrastructure. Malls often contain 50 to 100 acres, including the massive parking lots, and that’s the size of many planned communities and subdivisions. In some areas desperate for housing space, malls may provide a sensible solution.

In one California location, a 30-acre “green roof” is being considered, which would include almost 4 stay tunedmiles of public trails, vineyards and a wine bar.

It sounds as if future potential uses of our dying malls may only be limited by the imagination of developers. The developers I know and love have great imaginations, so stay tuned!

CFPB Structure Held Unconstitutional in PHH Case

Standard

Don’t get excited; this shouldn’t change much for SC dirt lawyers.

A three-judge panel of the U.S. Court of Appeals for the District of Columbia ruled unanimously on October 11 that the structure of the Consumer Financial Protection Bureau allows its director to wield too much power.

This highly publicized case began when PHH Corp. was ordered by CFPB Director Richard Cordray to pay $109 million in restitution resulting from illegal kickbacks to mortgage insurers pursuant to Section 8 of RESPA. An administrative law judge had ordered a $6 million penalty at the trial level, but Director Cordray apparently wanted to set an example and ordered the “ill-gotten gains” to be disgorged. The trial court had limited the violations to loans that closed on or after July 21, 2008. Director Cordray applied the fines retroactively.

scales - blue background

PHH brought suit, arguing that the CFPB is unconstitutional because Director Cordray has the sole authority to issue final decisions, rendering the CFPB structure to be in violation of the separation of powers doctrine. The petition stated, “Never before has so much authority been consolidated in the hands of one individual, shielded from the President’s control and Congress’s power of the purse.” The petition argues that the Director is only removable for cause, distancing him from the power of the President, and is able to fund the agency from the Federal Reserve’s operating expenses, distancing him from Congress’s power to refuse funding.

The Court agreed. It wrote, “Because the Director alone heads the agency without Presidential supervision, and in light of the CFPB’s broad authority over the U.S. economy, the Director enjoys significantly more unilateral power than any single member of any other independent agency.”

The restriction that the Director can only be removed “for cause” was severed, giving the President the power to remove the Director at will. This decision effectively makes the CFPB an agency of the Executive Branch rather than an independent agency.

The Court did not agree with Director Cordray imposing the huge fine retroactively. The Court explained:

“Put aside all the legalese for a moment. Imagine that a police officer tells a pedestrian that the pedestrian can lawfully cross the street at a certain place. The pedestrian carefully and precisely follows the officer’s direction. After the pedestrian arrives at the other side of the street, however, the officer hands the pedestrian a $1,000 jaywalking ticket. No one would seriously contend that the officer had acted fairly or in a manner consistent with basic due process in that situation. Yet that’s precisely this case. Here, the CFPB is arguing that it has the authority to order PHH to pay $109 million even though PHH acted in reliance upon numerous government pronouncements authorizing precisely the conduct in which PHH engaged.”

It is not likely that this landmark decision will make any changes in our current closing practices. The Court stated specifically that the ongoing operations of the agency will not be affected. The Court vacated the CFPB’s order and remanded the case for further proceedings. We might also see an appeal. Regardless, the CFPB is still in charge of the closing process, and all the rules remain in place.

Court of Appeals Revises Opinion, but not Result, in Arbitration Case

Standard

It seems the arbitration cases are all over the place in 2016. We’ve discussed three cases so far this year*, and the opinion in one of these cases has been withdrawn, substituted and refiled**, but the result did not change.

The South Carolina Court of Appeals decided to make a few changes in its opinion in One Belle Hall. The earlier opinion, filed June 1, held that an arbitration clause in a roofing supplier’s warranty provision was not unconscionable. The trial court had ruled that the supplier’s sale of shingles was based on a contract of adhesion and that the injured property owners lacked any meaningful choice in negotiating the warranty and arbitration terms, which were contained in the packaging for the shingles.

The Court of Appeals indicated that the underlying sale was a typical modern transaction for goods in which the buyer never has direct contact with the manufacturer to negotiate terms. The Court found it significant that the packaging contained the notation: “Important: Read Carefully before Opening” providing that if the purchaser is not satisfied with the terms of the warranty, then all unopened boxes should be returned. The Court pointed to the standard warranty in the marketplace that gives buyers the choice of keeping the goods or rejecting them by returning them for a refund, and blessed the arbitration provision.

knotted-road-sign

In the later opinion, filed September 28, the Court of Appeals addressed the South Carolina Supreme Court’s July 6, 2016 opinion in Smith v. D.R. Horton (cited in the footnote, below). In D.R. Horton, which this blog discussed on July, 14 the Supreme Court held that a national residential company’s contract contained a number of “oppressive and one-sided provisions”, including an attempted waiver of the implied warranty of habitability and a prohibition of awarding money damages of any kind. The Supreme Court held that the home purchasers lacked a meaningful ability to negotiate their contract, the only remedy through which appeared to be repair and replacement.

The difference in the two cases appears to be the location of the offending provisions. The United States Supreme Court has ruled that an arbitration agreement is separable from the contract in which it is embedded, and the issue of its validity is distinct from the substantive validity of the contract as a whole.*** The arbitration provision in D.R. Horton was construed in its entirety because various subparagraphs addressed warranty information and contained cross-references to each other. In addition, the contract did not contain a severability clause.

In the second opinion in One Belle Hall, the Court of Appeals admitted, as the supplier had conceded, that the agreement at issue was a contract of adhesion, but noted that our Supreme Court has stated that adhesion contracts are not per se unconscionable. The Court recognized that the roofing supplier’s contract continuously used language to the effect that any attempted disclaimer or limitation did not apply to purchasers in jurisdictions that disallowed them. The Court also found it significant that the agreement contained a severability clause.

In other words, since the objectionable provisions of the contract were outside the arbitration provision, and the arbitration provision is severable from the objectionable provisions, the arbitration clause is enforceable. The Court repeated its earlier point that the arbitration provision facilitates an unbiased decision by a neutral decision maker in the event of a dispute.

I believe we will see more of these cases, and I caution lawyers to be extremely careful in their drafting endeavors.


*  One Belle Hall Property Association v. Trammel Crow Residential Company, S.C. Ct. App. Opinion 5407 (June 1, 2016); Smith v. D.R. Horton, Inc., S.C. Supreme Court Opinion 27642 (July 6, 2016); and Parsons v. John Wieland Homes, S.C. Supreme Court Opinion 27655 (August 17, 2016).

**  One Belle Hall Property Association v. Trammel Crow Residential Company, S.C. Ct. App. Opinion 5407 (September 28, 2016)

***  Prima Paint Corporation v. Flood Conklin Mfg. Co., 388 U.S. 395 (1967)

New Settlement Agent Communication from Wells Fargo

Standard

Seller CD must be provided to Wells prior to disbursement

Wells Fargo communicated with its settlement agents (closing attorneys in South Carolina) by memo dated September 22. In case you missed it, you can read it in its entirety here.

The biggest news is that Wells will now require a copy of the seller Closing Disclosure along with the other documents required prior to disbursement. Apparently, receipt of the seller CD has been a challenge, necessitating the procedural modification.

StageCoachLogo

Another challenge has been the process for handling changes to the borrower’s CD. The memo stated that any changes known prior to closing, including changes to the closing numbers, the closing date and the disbursement date, must be communicated to the Wells Fargo closer.  Wells Fargo’s closer will provide an updated borrower CD and any other updated documents for closing.

Any changes detected at or post-closing should be communicated to:  SAPostClosingCommunications@wellsfargo.com.

The memo also discussed the phased rollout in progress for delivering training materials and other support for the use of Closing Insight™.  We encourage closing attorneys to read and comply with this information to avoid being left out when this process is fully implemented.

Ransomware: A Scary Prospect for Dirt Lawyers

Standard

The Cyberdivision of the FBI is serious about ransomware!  An FBI speaker last Friday at the SC Bar’s excellent tech seminar, an annual seminar I highly recommend for solo and small firm lawyers, emphasized awareness and employee training are critical to prevent data losses in your operation.

Ransomware is a form of malware that is most often delivered through spear phishing e-mails. Spear phishing is a type of e-mail fraud that seeks unauthorized access to confidential data. Ransomware is what it sounds like. Once the fraudster gains access, your system is locked down, and money is demanded to provide access. You have to pay for your own data!

hacker

“H4ck3rz R Us, how can I help you?”

The FBI recommends prevention, business continuity and remediation, but suggests that there is no guarantee of prevention even with the most robust controls in place. Methods of prevention include:

  • Provide extensive awareness and training for your staff.
  • Use strong anti-virus and anti-malware solutions that are set up to update automatically.
  • Regular scans should be conducted of the anti-virus and anti-malware solutions.
  • No user should be assigned administrative access unless that access is absolutely needed.
  • Those with administrative accounts should only use them when necessary.
  • Keep access to a minimum. If a user only needs specific files, he or she should not have access to other files.
  • Ask your IT professionals to implement controls to avoid common ransomware techniques.

But since prevention is not guaranteed, the most attention should be paid to business continuity and remediation. In short, back up your data regularly and regularly verify the integrity of the backups.  Secure backups. Ensure backups are not connected to the computers and networks they are backing up.

The FBI does not endorse paying a ransom to the fraudsters and teaches that paying the ransom does not always ensure regaining access to data.

The FBI encourages victims to contact a local FBI office immediately to report a ransomware attempt and to request assistance. Victims are also encouraged to report cyber events to the FBI’s Internet Crime Complaint Center (www.ic3.gov.)

Don’t Amend Your Master Deed As A Litigation Strategy

Standard

The South Carolina Court of Appeals was not impressed!

The owners of The Gates at Williams-Brice (a great place to tailgate!) were surprised in 2012 when a maintenance company refused to bid on an exterior caulking/sealant job because of perceived construction defects.  Almost immediately, the owners’ association and an individual owner filed a complaint alleging negligence, gross negligence, breach of warranty and strict liability claims. The defendants were numerous developer and contractor entities.

The plaintiffs demanded a jury trial and sought to establish a class action for the condominium owners. The developer filed a motion for a nonjury trial and to strike the class action allegations. The Circuit Court ruled for the plaintiffs, and the defendants appealed. The Court of Appeals, in an Opinion dated August 31*, reversed.

The case contains several practice pointers for dirt lawyers, especially those who draft master deeds and amendments to master deeds and those who represent owners’ associations.

williams-brice

The Master Deed establishing The Gates at Williams-Brice contained provisions requiring arbitration, waiving the right to a jury trial, waiving the right to a class action, and eliminating the right to secondary, incidental or consequential damages.

The original complaint was filed in December of 2012. An answer, opposing the certification of a class, was filed in May of 2013. Later that month, the complaint was amended to add defendants. And on May 23, the homeowners amended the Master Deed to remove the provisions that thwarted their litigation efforts.

The Circuit Court found that the provisions at issue were no longer within the Master Deed and that the defendants were precluded from enforcing unconscionable arbitration and alternative dispute resolutions that contained oppressive, one-sided terms.

On appeal, the defendants argued that the Master Deed could not be amended retroactively to remove the provisions at issue. Neither party contested that the homeowners’ actions were taken in anticipation of litigation. The Court of Appeals held that the homeowners knowingly, voluntarily and intelligently waived their rights to a jury trial and to a class action when they signed their deeds.

Citing a North Carolina case**, the Court of Appeals said that to remove the agreed-upon waivers retroactively would effectively substitute a new obligation for the original bargain of the parties. The Court pointed to the cites in the North Carolina case that indicate several jurisdictions apply a reasonableness standard when reviewing amendments to covenants and holding a provision authorizing an owners’ association to amend covenants does not permit amendments of unlimited scope; rather, every amendment must be reasonable in light of the contracting parties’ original intent.

The Court of Appeals discounted several cases involving amendments in condominium projects by the Circuit Court as not controlling. One such case found the developer’s amendment to increase maintenance assessments was enforceable against new purchasers. Another case approved an amendment regarding leasing restrictions. A third case found that an owners’ association properly amended covenants to prohibit the developer from advertising on the property. The final case held that an amendment authorizing the association to suspend utilities for unpaid judgments was properly applied against a unit owner because any alleged retroactivity was proper based on the contractual relationship between the association and the unit owner.

Other cases cited by the Circuit Court were dismissed as neither dealing with amendments to condominium declarations nor to master deeds.

The Court stated that it was unaware of any authority in South Carolina that would permit contracting parties to unilaterally alter agreed upon provisions once litigation has started.

The developer also argued that the amendments were ineffective because they failed to obtain the required permission of lenders and other “bound parties” such as the developer. The Court declined to address that issue because of its other conclusions.

What will the Supreme Court say if it gets the opportunity to rule on this issue?


*The Gates at Williams-Brice Condominium Association v. DDC Construction, Inc., S.C. Court of Appeals Opinion 5438 (August 31, 2016)

**Armstrong v. Ledges Homeowners Ass’n, Inc., 633 S.E.2d 78 (N.C. 2006)